★★★★★
David Rodriguez was professional and comforting at the same time. I'm 72 and on a fixed income, and he went above and beyond to find me a $15,000 policy I could actually afford. He never once made me feel pressured.
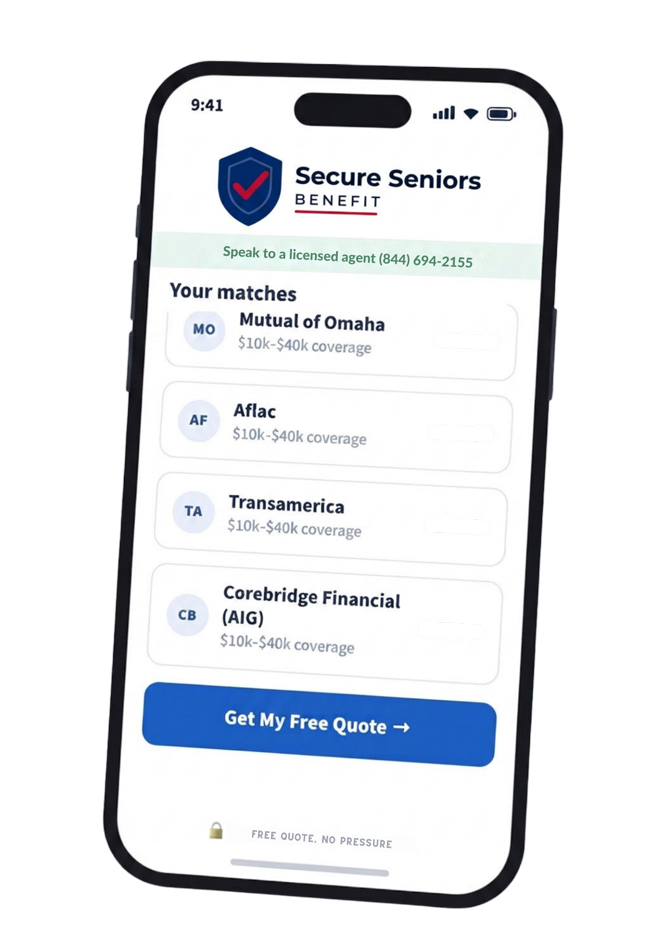
We compare well-known carriers side by side, including the brands you've seen on TV, to find your lowest price for your age and health. FREE, and with no obligation.
Answer a few quick questions and a licensed agent finds the price that fits you.
Get My Free Quote →No obligation. No pressure. Licensed agents only.
Day 1 coverage options are available for many ages and health conditions.
You've seen these names on television and in the mail. Rather than ask you to take our word for it, you'll find each company’s independent financial strength rating below. A fact you can check yourself in about a minute.
Consistently competitive on simplified-issue final expense across a wide range of health profiles.
A household name with simplified-issue whole life options for final expense.
Long-established carrier with a broad range of final expense products.
Best known for the guaranteed-acceptance plan advertised on daytime television. Sold direct to consumers.
Known for low advertised starter premiums marketed by mail. Sold direct to consumers.
The former AIG Life & Retirement business. Offers guaranteed-issue options for applicants who can't answer health questions.
Please read this part. Some companies shown here sell only directly to consumers and aren't available through Secure Seniors Benefit. We include them so you can see how your options compare. Which carriers a licensed agent can actually offer you depends on your state, your age and your health. Product features differ: some advertised plans include a waiting period or a graded death benefit.
A.M. Best Financial Strength Ratings shown were published by A.M. Best and checked on 20 August 2026. Ratings change. You can verify any of them free at ambest.com. All carrier names and trademarks are the property of their respective owners and appear here for identification and comparison only.
This is the question everybody asks first, and most websites refuse to answer it. Honest ballpark ranges for a $10,000 whole life policy, non-tobacco, simplified issue, the most common starting point.
| Your age | Women | Men |
|---|---|---|
| 50–54 | $28 – $40 | $35 – $50 |
| 55–59 | $33 – $48 | $42 – $60 |
| 60–64 | $40 – $58 | $50 – $72 |
| 65–69 | $48 – $70 | $60 – $88 |
| 70–74 | $62 – $92 | $80 – $125 |
| 75–79 | $85 – $125 | $100 – $145 |
These are illustrative estimates, not quotes. They are ranges compiled from publicly published 2026 final expense rate research, including MoneyGeek and Choice Mutual, checked 20 August 2026. Your actual premium depends on your age, gender, state, tobacco use, health answers, the coverage amount you choose and the carrier’s underwriting. Tobacco use typically raises the premium substantially. Nothing here is an offer of coverage.
Roughly covers a direct cremation with a simple service, or makes a serious dent in a basic burial.
The range most families land on. Enough for a full funeral with viewing and burial, plus a little left over.
Covers the funeral and leaves money behind for final medical bills, small debts, or a gift to family.
Three simple steps. It takes about 60 seconds to start.
A few quick questions about your age and health. No exam. No paperwork.
We compare trusted companies side by side. Then we show you who's cheapest for you.
You choose. No pressure. Our help is always free.
Final expense insurance isn't designed to make anybody rich. It's designed to do one job well: make sure the funeral is paid for without your family having to find the money.
You answer health questions instead. Having health conditions doesn't mean an automatic denial. It usually just changes which company is the right fit.
Many applicants qualify for plans that pay the full benefit from the first day. Where they don't, an agent should tell you plainly and explain the waiting period.
Once a whole life policy is issued, the premium doesn't go up as you age or if your health gets worse. Budget it once.
Unlike some plans advertised on television, the amount your family receives doesn't decrease as you get older, and the coverage doesn't expire.
The benefit is paid to the person you name, generally income-tax-free, and they can spend it on whatever they actually need.
Age qualification varies by plan and carrier, and the insurance company always decides, never us.
An honest look at your options.
| What you want |  Secure Seniors Benefit | Most insurance agencies | Other insurance websites |
|---|---|---|---|
| Compare big-name companies side by side | ★★★★★ | ★★★★★ | ★★★★★ |
| Instant online quotes | ★★★★★ | ★★★★★ | ★★★★★ |
| Real help from licensed agents | ★★★★★ | ★★★★★ | ★★★★★ |
| Upfront about how we get paid | ★★★★★ | ★★★★★ | ★★★★★ |
| No-pressure, no-obligation help | ★★★★★ | ★★★★★ | ★★★★★ |
| Simple application | ★★★★★ | ★★★★★ | ★★★★★ |
| Waiting periods explained before you buy | ★★★★★ | ★★★★★ | ★★★★★ |
| Final expense specialists | ★★★★★ | ★★★★★ | ★★★★★ |
Our honest assessment of typical experiences by category, not ratings of any specific company. Ratings reflect our own opinion and are not independent research.
Real feedback from people who compared final expense coverage with us. Shared with their permission.
David Rodriguez was professional and comforting at the same time. I'm 72 and on a fixed income, and he went above and beyond to find me a $15,000 policy I could actually afford. He never once made me feel pressured.
Mr. Marshall Ott did an excellent job putting my worries at ease. I had my grandkids with me and he was so patient when I had to step away to tend to them. By the time we hung up, everything was set up and I finally felt a weight lifted.
This company is great! The representative was honest and thorough with me. He made sure I understood every detail before I signed anything. I already recommended them to my sister.
My experience was extremely smooth. Mason answered every question I had — and I had a lot of them. His patience and compassion were outstanding. I got my policy in place the very same day.
Very professional, polite and courteous. He explained everything in plain English, which I appreciated. I was surprised how quick and easy the whole thing was — about 20 minutes on the phone and I was done.
Christian Smith helped me choose my burial plan and he was a pleasure to deal with. He was professional the whole time, yet easy to talk to like family. I never felt confused or rushed into anything.
Andrew Riste was impressive and really knew his stuff. After he explained exactly what I was getting, I knew right away I was in good hands. It's a comfort knowing my funeral costs won't fall on my daughter.
Mason was such a compassionate broker. He took his time and made sure I understood everything before I said yes. I can sleep better now knowing my children won't be left with that burden.
Sergeant Webb was an amazing help to me. He answered all my questions and found me coverage that fit my budget. My concerns for myself and my family are now put to rest because of his care and diligence.
My experience with Itzel was amazing. She was kind, patient and explained everything so I could understand it. She helped me get a policy I can afford on my pension, and I'm grateful.

Bryon was understanding and respectful of my wishes. He explained everything in detail and answered all my questions. I trust him, and I don't trust easy.

My experience with Ms. McPhail went smoothly from start to finish. She was knowledgeable and professional, and she got me set up with a $10,000 policy for under $50 a month. I couldn't be happier.
Reviews reflect individual customer experiences and do not guarantee specific rates or outcomes. Rates vary by age, health and state.
If something is free, you're right to wonder who is paying for it. So the whole arrangement, in plain English:
You pay us nothing, ever. Comparing your options costs you nothing, whether you buy a policy or not.
We're a marketing company, not an insurance agency. We don't sell, negotiate or issue insurance, and we're not licensed to give you insurance advice.
We connect you with licensed agents. When you submit the form or call, your information goes to independent licensed insurance agents and agencies, the people actually qualified to quote you.
Those agents and their partners compensate us for the introduction. That payment is how this site stays free to you. It doesn't come out of your premium as an extra fee, and it doesn't change the rate the carrier charges.
We don't control what happens on the call. We don't employ those agents, write their scripts, or set their prices. If one of them treats you badly, tell us and tell your state insurance department.
The honest summary: we're paid to introduce you to someone licensed. You're free to take the information and walk away.
One more thing we won't pretend about: your information is shared with our marketing partners and lead buyers when you submit the form. That's stated plainly in the consent language on our quote form and in our Privacy Policy and terms and conditions.
These come up constantly in public discussions about burial insurance. They deserve straight answers rather than reassurance.
“Am I going to get pressured the second I pick up the phone?”
This is exactly what happens. A licensed agent asks your age, your state, and a short list of health questions. They tell you which companies will accept you and what each one charges. Then they ask if you want to apply. “No thank you” ends the call. You don't need a reason, and you can hang up at any point.
“Will I end up paying in more than my family gets back?”
Possibly. And any agent who tells you otherwise isn't being straight with you. If you buy at 60 and live to 95, you may well pay in more than the death benefit. Insurance is protection against dying sooner than expected, not an investment. If you're healthy, disciplined, and confident you can save the full amount and not touch it, saving may genuinely serve you better. We'd rather say that than sell you something you don't need.
“Is this one of those TV plans that gives you almost nothing?”
Some heavily advertised plans are sold in small “units” rather than a stated coverage amount, and the actual benefit at your age can be far less than people expect. That's precisely why comparing matters. Always ask one question: “What is the exact dollar amount my family receives, and when?” A good agent answers it immediately.
“What if I'm turned down because of my health?”
Most people aren't turned down. They're moved to a different type of plan. Simplified issue asks a few health questions and can pay from day one. Guaranteed issue asks none at all and accepts nearly everyone, but almost always carries a two-year waiting period for natural causes. Both are real coverage. The difference matters enormously, and you should be told which one you're being offered.
These concerns are drawn from public online discussions among people shopping for burial insurance. They're presented as questions this site answers. They aren't testimonials, endorsements, or statements by our customers.
It's a small whole life policy, usually between $2,000 and $50,000, meant to cover a funeral, burial or cremation, and any final bills. It doesn't expire, the premium doesn't rise, and the money goes to whoever you name.
In most cases, yes. Controlled diabetes and many heart conditions are routinely accepted on simplified-issue plans with day-one coverage. More serious conditions may point you toward a guaranteed-issue plan, which accepts nearly everyone but carries a two-year waiting period for natural causes. Read the full guide on health conditions.
It depends on the plan. Many people qualify for day-one coverage, meaning the full benefit is payable immediately. Guaranteed-issue plans typically pay only your premiums back plus interest if you die of natural causes within the first two years. Accidental death is usually covered in full from day one on both. Always ask which type you're being offered.
Probably not. Most carriers write final expense coverage between ages 50 and 85, and some go further. Age qualification varies by plan and carrier, and acceptance is decided solely by the insurance company.
We're a marketing company. Licensed agents and their partners pay us for connecting them with people who want a quote, which is why it costs you nothing. We have written out the whole arrangement in detail rather than burying it.
It takes about a minute, it's free, and nobody can make you buy anything.
Free. No obligation. You'll speak with a licensed insurance agent.